
-

Macro and markets, Cash management, Technology
Up to the atmosphere with CBDCs
In the second part of their 2023 three-part series on The Future of Money, Deutsche Bank Research analysts Marion Laboure and Cassidy Ainsworth-Grace revisit the stellar rise of central bank digital currencies (CBDCs). flow’s Clarissa Dann provides a summary of their key findings
MINUTES min read
According to the Deutsche Bank Research dbDIG proprietary survey conducted in September 2023, one in five consumers believe that CBDCs will become mainstream. “We have no doubt: the question is no longer if but when the CBDC economic rocket will take off,” reflect Deutsche Bank Research analysts Marion Laboure and Cassidy Ainsworth-Grace in the second report from their three-part series, The Future of Money, entitled CBDCs: The Economic Rocket Takes Off.
Almost three years ago, the flow article “Digital currencies, differing motives” reported that only around 35 of the world’s central banks had embarked on initiatives to develop their own CBDCs. With the Covid-19 pandemic having added impetus to the trend – that number has now grown to 130, with several countries having already launched a CBDC.
Laboure and Ainsworth-Grace have identified the sea change that saw central banks move to an increasingly positive view of CBDCs occurring towards the end of 2018. Earlier in 2023, in the flow article “Digital currencies: the ultimate soft power?”, the duo considered whether the acceleration of CBDCs over the past five years owed much to their emergence as a soft power tool at a time of geopolitical volatility.
“The question is no longer if but when the CBDC economic rocket will take off”
Current position
Emerging economies are leading the race, with four live retail CBDCs. The Chinese government has also made significant efforts to promote its CBDC. Advanced economies are making progress –in October, the European Central Bank (ECB) has provided the green light to proceed with the next phase of the digital retail euro project, the ‘preparation phase’. While retail CBDC projects are far ahead of wholesale projects, central banks are now speeding up wholesale research – this article provides further information on their progress.
There are two types of CBDC – retail (used by consumers and households in everyday transactions) and wholesale (used by financial institutions and central banks). Figure 1 provides a summary of the main characteristics of each.
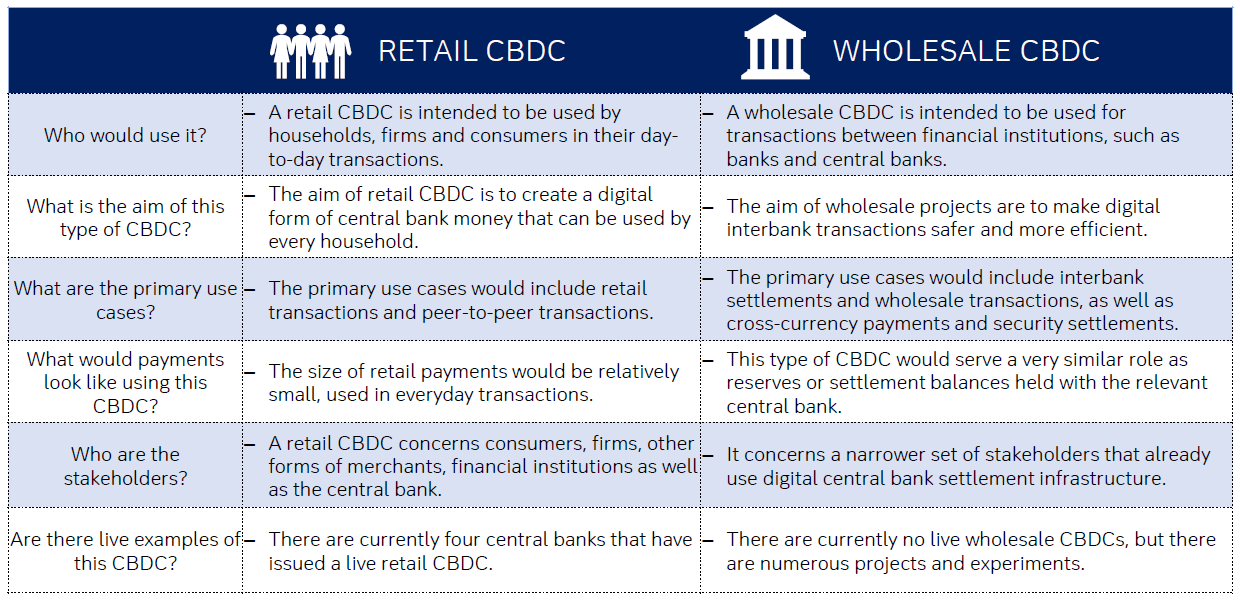
Figure 1: The two types of CBDC
Source: Deutsche Bank, Kosse, A. and Mattei, I. (2023), 'Making headway - Results of the 2022 BIS survey on central bank digital currencies and crypto', BIS Papers, No. 136
Figure 2 demonstrates how far individual countries have got to with their retail and wholesale CBDC journeys as of July 2023.
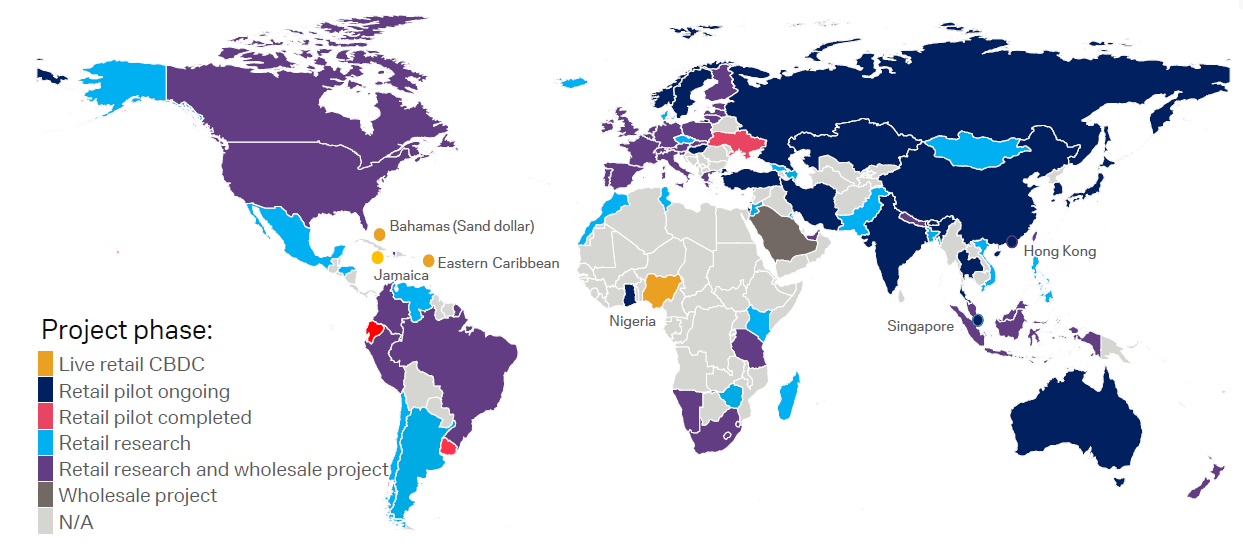
Figure 2: CBDC global heatmap
Source: CBDC Tracker, R Auer, G Cornelli and J Frost (2020), "Rise of the central bank digital currencies: drivers, approaches, and technologies", BIS working papers, No 880, August. Updated as of July 2023, latest update by Auer et al (2023)
Wholesale CBDCs
While work on retail CBDCs is more advanced than for wholesale CBDCs, more central banks are now focused on developing both, report Laboure and Ainsworth-Grace.
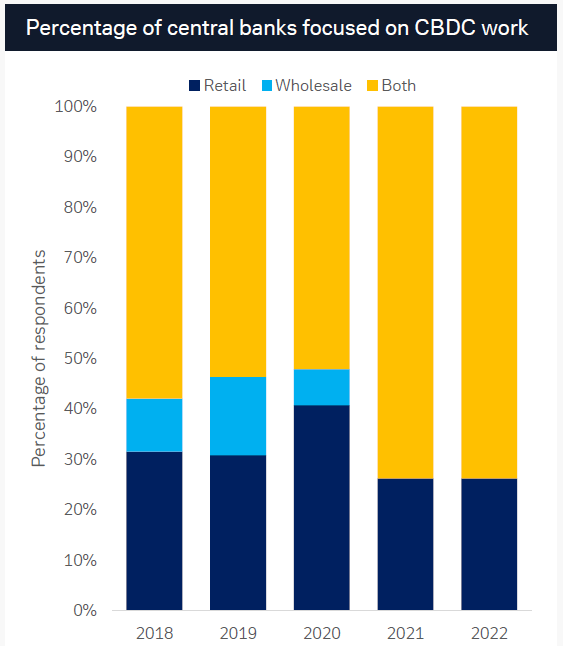
Figure 4: More central banks are focusing on wholesale CBDCs
Source: Deutsche Bank, Federal Reserve Bank of New York and the Monetary Authority of Singapore (2023), 'Project Cedar Phase II x Ubin +', at https://www.newyorkfed.org/medialibrary/media/nyic/project-cedar-phase-two-ubin-report.pdf, Kosse, A, and Mattei, I. (2023), 'Making headway - Results of the 2022 BIS survey on cental bank digital currencies and crypto', BIS Papers, No. 136. How new tech and CBDCs can simplify payments - Deutsche Bank Corporate Flow
Several major experiments to develop a wholesale CBDC are underway. In May 2023, the Federal Reserve Bank of New York and the Monetary Authority of Singapore (MAS) published a joint report on Project Cedar x Ubin+, their wholesale CBDC experiment on cross-border wholesale payments and settlements involving multiple currencies.3
Cedar x Ubin+ tested a multiple wholesale CBDC design, whereby countries and other participants operated their own distinct CBDC network according to their needs. These networks were able to interact due to relying on a shared technical interface/clearing mechanism like an application programming interface (API). It enabled the two central banks to interact and transact with each other without being onboarded to a single network.
This is how it works:
- When a payment leg is initiated, the acting party’s tokens are locked using a hashed secret generated by the other party.
- The second payment leg is initiated on a separate network, similarly locked, and linked to the first.
- The initiating party may then claim the CBDC tokens owed after the secret is revealed – as can the counterparty.
The report findings addressed three pain points: interoperability and autonomy; interlinking of distinct central bank currency ledgers; and providing flexibility in design and operation.
Transactions were only settled if all legs in the cross-currency payment chains were executed successfully, but near real-time settlement was achievable with end-to-end settlement in under 30 seconds. Test simulations resulted in an average of 6.5 payments per second, peaking at 47 payments per second.
In Europe, lead actors are the Banque de France and the European Investment Bank, which have run several wholesale CBDC experiments. France’s central bank reported in July that a CBDC could improve cross-border payments, settlement finality, and security for a vast range of assets. At the start of 2023, the European Investment Bank (EIB) issued its first digital bond in pounds, valued at £50m, via a combination of private and public blockchains.4
Having decided in only a few years that CBDCs might be a worthwhile concept after all, the authors conclude their report with a synopsis of what the implications are of digital currencies for the banking sector, corporates and payment services providers (see Figures 5 and 6).
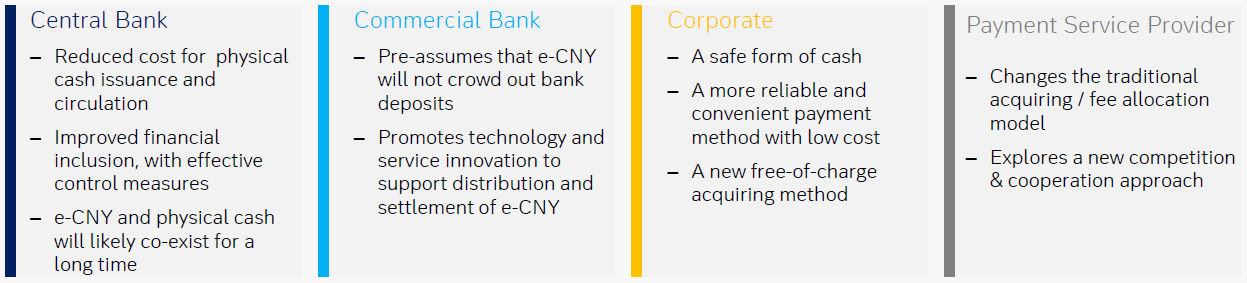
Figure 5: Potential implications of digital currencies
Source: Deutsche Bank
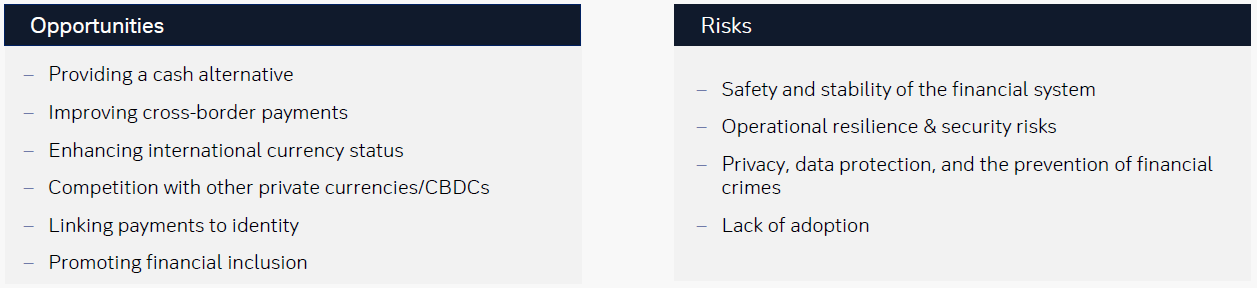
Figure 6: Opportunities and risks of digital currencies
Source: Deutsche Bank
“If CBDCs are designed prudently, they can potentially offer more resilience, more safety, greater availability, and lower costs than private forms of digital money”, said IMF Managing Director Kristalina Georgieva in February 2022.5 Eighteen months later, it is all about adoption and appetite.
Deutsche Bank Research report referenced:
The Future of Money – Part 2. CBDCs: The Economic Rocket Takes Off by Marion Laboure and Cassidy Ainsworth Grace (September 2023)


You might be interested in
CASH MANAGEMENT, MACRO AND MARKETS, SECURITIES SERVICES
Digital currencies: the ultimate soft power? Digital currencies: the ultimate soft power?
Central bank digital currencies (CBDCs) are the vehicle for central banks worldwide to develop their own digital payment alternatives. Not only are emerging market economies ahead of developed ones in launching them but CBDCs are also emerging as a soft power tool at a time of geopolitical volatility. flow’s Clarissa Dann provides a summary of a recent Deutsche Bank Research report
CASH MANAGEMENT, MACRO AND MARKETS
CBDCs: what’s not to love? CBDCs: what’s not to love?
As Jamaica prepares to launch its own central bank digital currency and China’s digital yuan is fast gaining traction, Deutsche Bank Research’s recent white paper on the future of cash offers a progress report on CBDC launches and initiatives. flow shares its core findings
CASH MANAGEMENT, MACRO AND MARKETS
Japan joins the journey to a cashless society Japan joins the journey to a cashless society
Japan might be a relative latecomer to journey towards a cashless society, but it has made swift progress in just five years, as a Deutsche Bank Research paper reports